Can a First-Time Buyer Close on a Kansas City Home With Less Than $1,000?
How We Helped a First-Time Buyer Land Her First Home in Crestview, Kansas City, MO — The Full Story
Yes — With FHA Financing and Seller Concessions Doing the Heavy Lifting. Here Is How It Went in Crestview
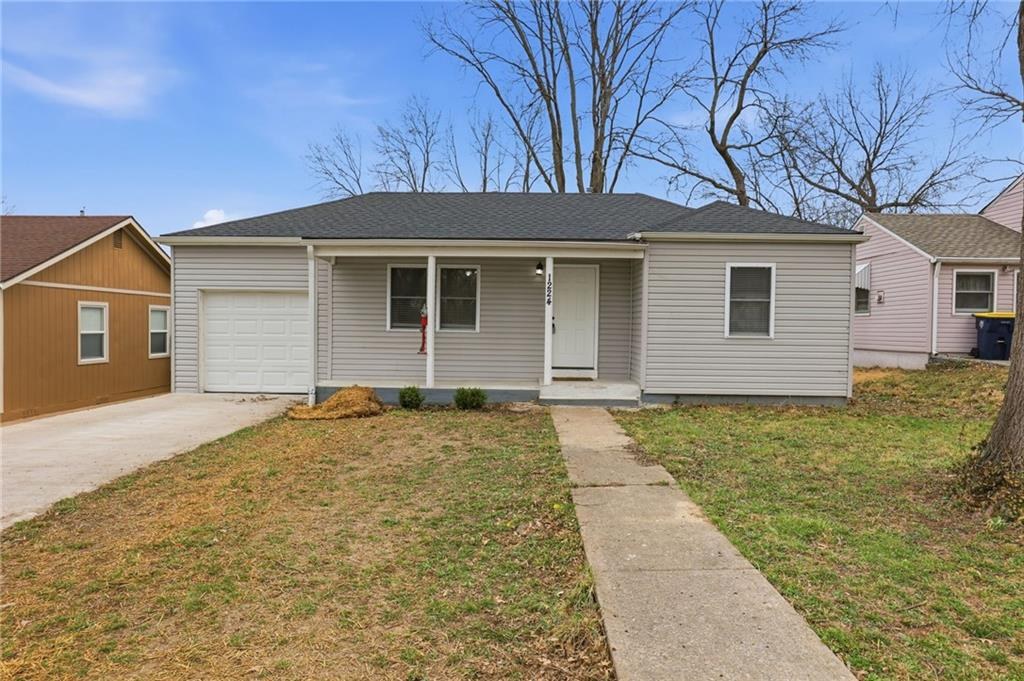
Yes, a first-time buyer can close on a home in Kansas City with less than $1,000 at the closing table — but not by accident, and not by finding a house that is somehow cheaper than the rest. It takes the right loan, a negotiated seller credit, and an offer written so the two work together. In June 2026 a first-time buyer working with Danny Stansbury of Nelson Home Group at Keller Williams KC North bought a two-bedroom 1953 ranch in the Crestview subdivision of Kansas City, Missouri, on FHA financing with $6,323 in seller-paid concessions. She brought less than $1,000 to closing on June 16, 2026.
The number that stops most first-time buyers in the Northland is not the price. It is the cash due at closing — down payment, lender fees, title charges, prepaid taxes and insurance, all landing on the same day. This buyer said exactly that before she ever looked at a house. What follows is how the deal was structured so that number came down, on a listing that had just watched another buyer’s financing collapse on closing day.
Here is how it actually went, start to finish.
The Full Story
Seven years before this closing, Joe Nelson helped a young woman named Elizabeth buy her first home. When her mother was ready to buy a house of her own, Elizabeth came back to the same team — and the file landed with Danny Stansbury, the newest agent at Nelson Home Group. This would be his first closed transaction.
The buyer was clear about one thing from the start. In her words: “Honestly, I was most worried about how much money I was going to need to bring to closing.” That is the most common fear we hear from first-time buyers, and it is the one that keeps people renting for years longer than they need to. The purchase price gets all the attention, but the cash due at the closing table is what actually decides whether a purchase happens.
There was a second thing about this transaction that shaped how it had to be run. The buyer spoke limited English, and Elizabeth translated at every step of the process. Every number got explained twice. Every document was walked through until both of them understood it. Nothing was assumed, and nothing was signed in a hurry. For a new agent on his first deal, that is a demanding way to learn the job — and it is also the right way.
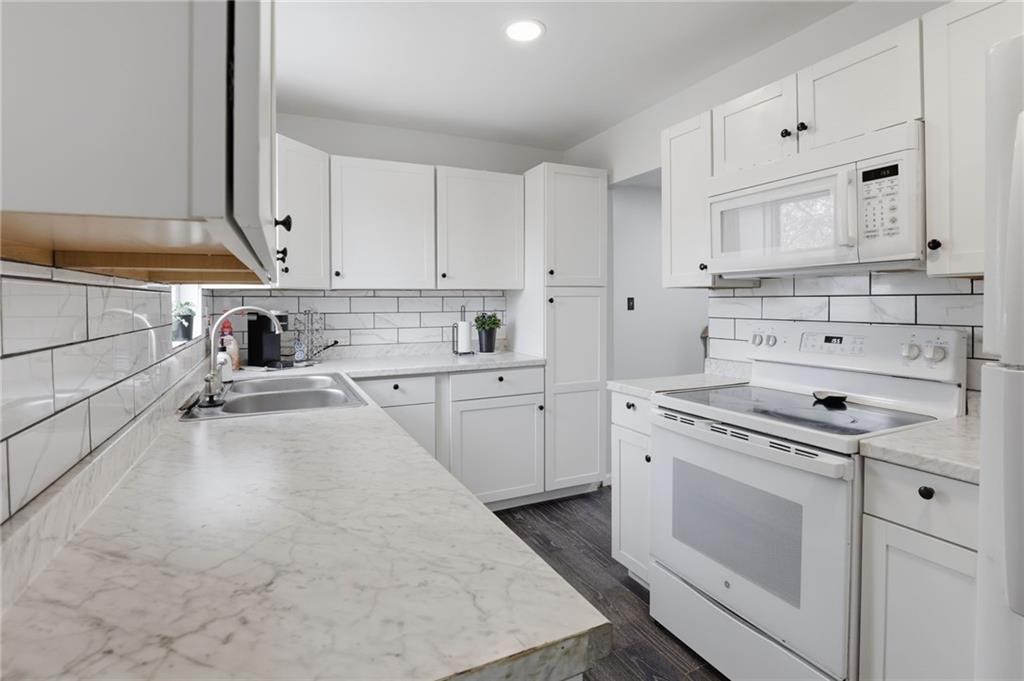
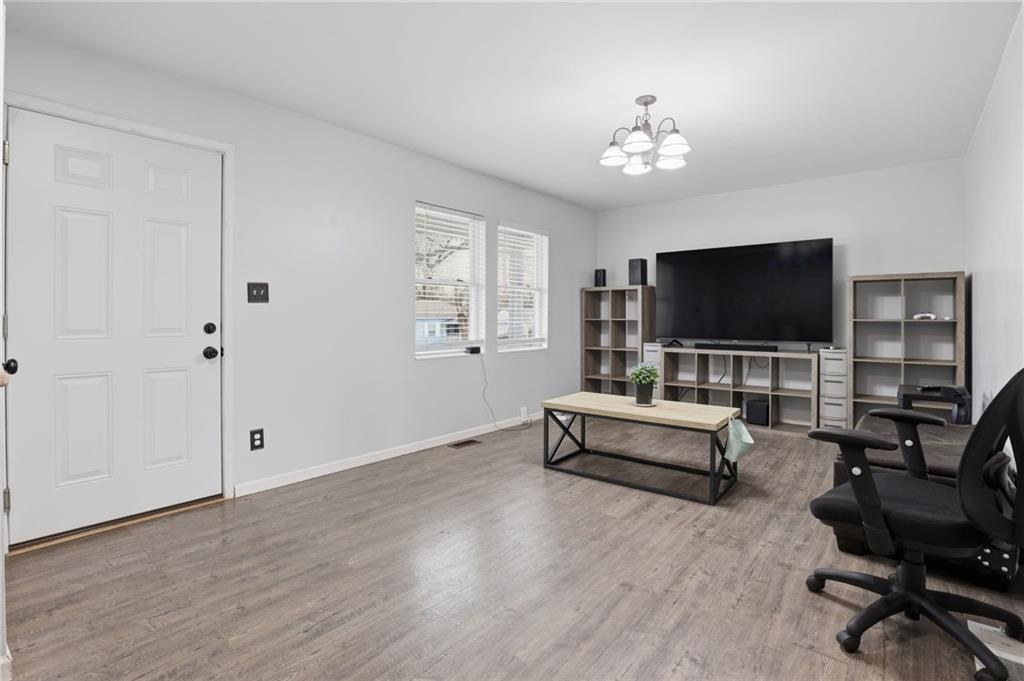
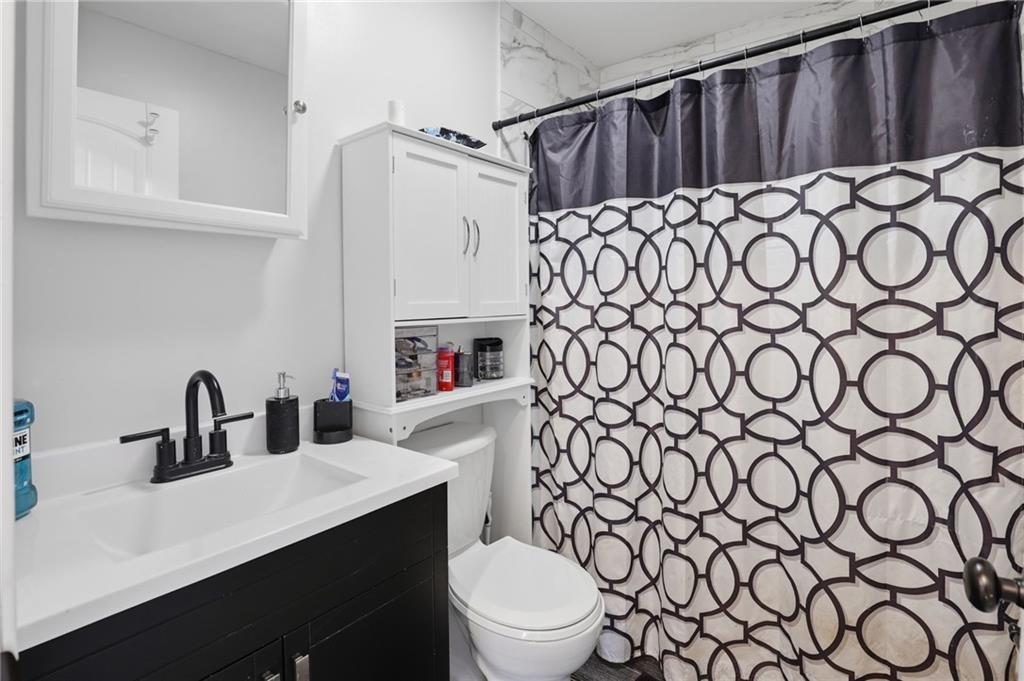
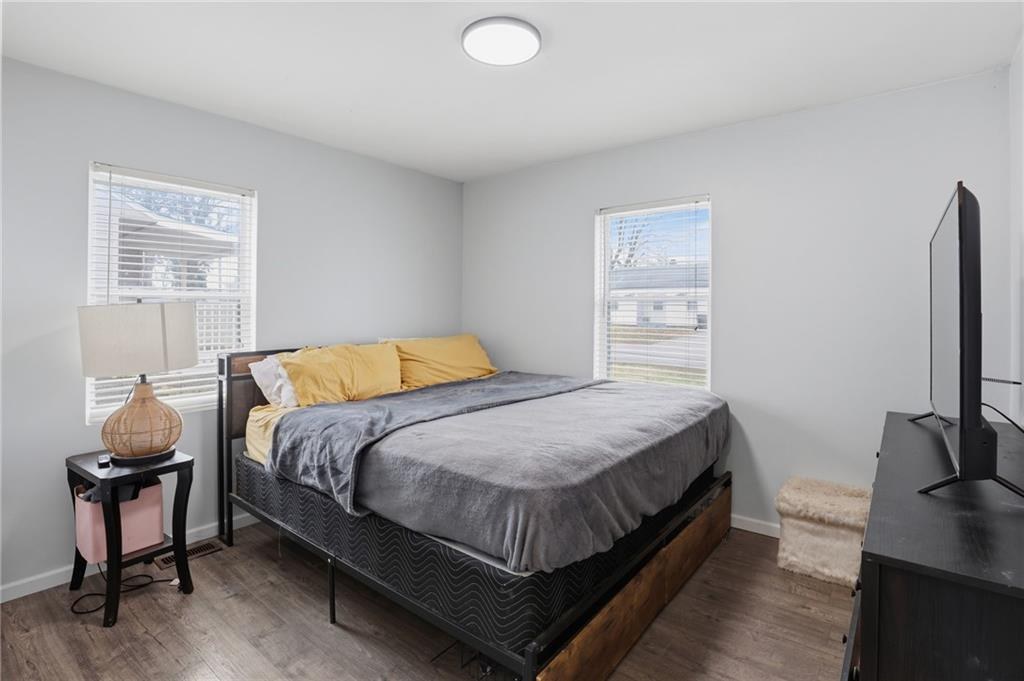
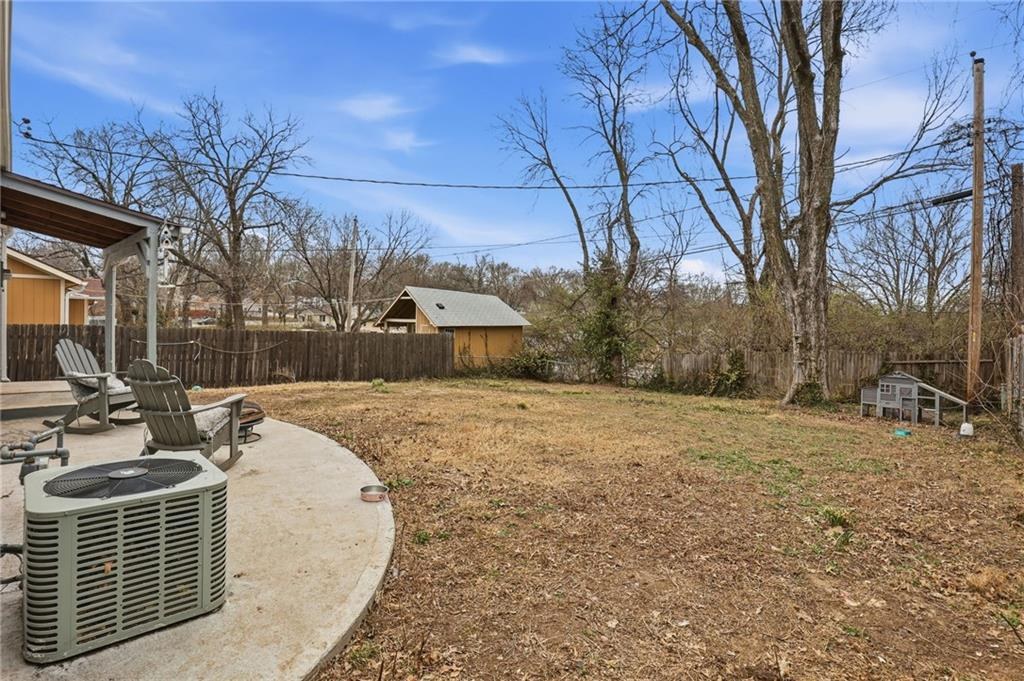
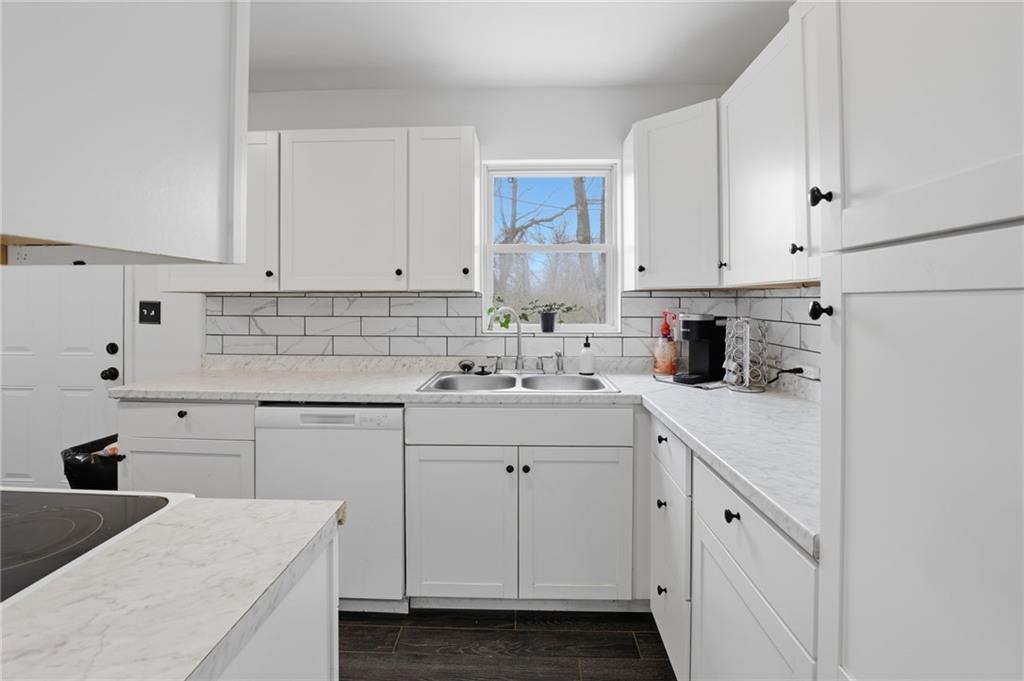
The house had come on the market March 23, 2026. It is a two-bedroom, one-bath ranch built in 1953 in the Crestview subdivision, with 688 square feet on one level, an attached one-car garage, a covered front porch, and a fenced backyard with a patio on a 0.14-acre lot. The seller had updated it — a white kitchen with a subway-tile backsplash, laminate floors, a redone bathroom, central electric heat and air — and it was move-in ready. It is served by the North Kansas City School District and sits in Clay County, minutes from Antioch Road and I-35.
By the time Danny’s buyer saw it, the listing had a history. The public MLS remarks said it plainly: “Back on the market, buyer’s financing fell apart on closing day.” A previous buyer had gone all the way to the finish line and been unable to fund. The seller had lost weeks and was starting over — which meant the next offer was going to be judged on one question above every other: is this financing going to hold?
“The purchase price gets all the attention. The number that actually stops people is the cash due at the closing table — and that number can be negotiated.”
The Strategy
The financing was FHA. For a first-time buyer with limited cash, FHA’s 3.5 percent minimum down payment is the starting point, but down payment is only part of the cash-to-close number. Closing costs, lender fees, title charges and prepaids on a purchase in this price range can add several thousand dollars more — and that is the money most first-time buyers do not have sitting in an account.
So the offer was written to solve for cash, not for the lowest possible price. Danny’s offer went above the list price and asked the seller for $6,323 in concessions back toward the buyer’s closing costs and prepaids. The seller nets roughly the same money either way; the buyer finances the concession over the life of the loan instead of writing a check for it on closing day. It is one of the oldest tools in the business, and it only works if two things are true: the home has to appraise at the higher price, and the seller has to believe the financing will actually close.
That second point was the whole negotiation here. A seller who has just been burned by a financing failure on closing day does not accept an FHA offer with a concession request unless the buyer’s file is solid and the lender is responsive. It was, and they were. The seller accepted, and the home went under contract May 14, 2026.
From there the job was to keep the deal boring: inspection, appraisal, underwriting, and a closing date that did not move. The buyer’s word for it afterward was “surprised”: “I was surprised by how smoothly everything went and how Danny helped make the numbers work.”
The Success
The purchase closed June 16, 2026, 33 days after going under contract, on FHA financing.
Final terms: an offer written above the list price with $6,323 in seller-paid concessions credited back at closing, and a buyer who brought less than $1,000 to the table for her first home. The MLS records 13 days on market for the listing after it came back from the failed contract.
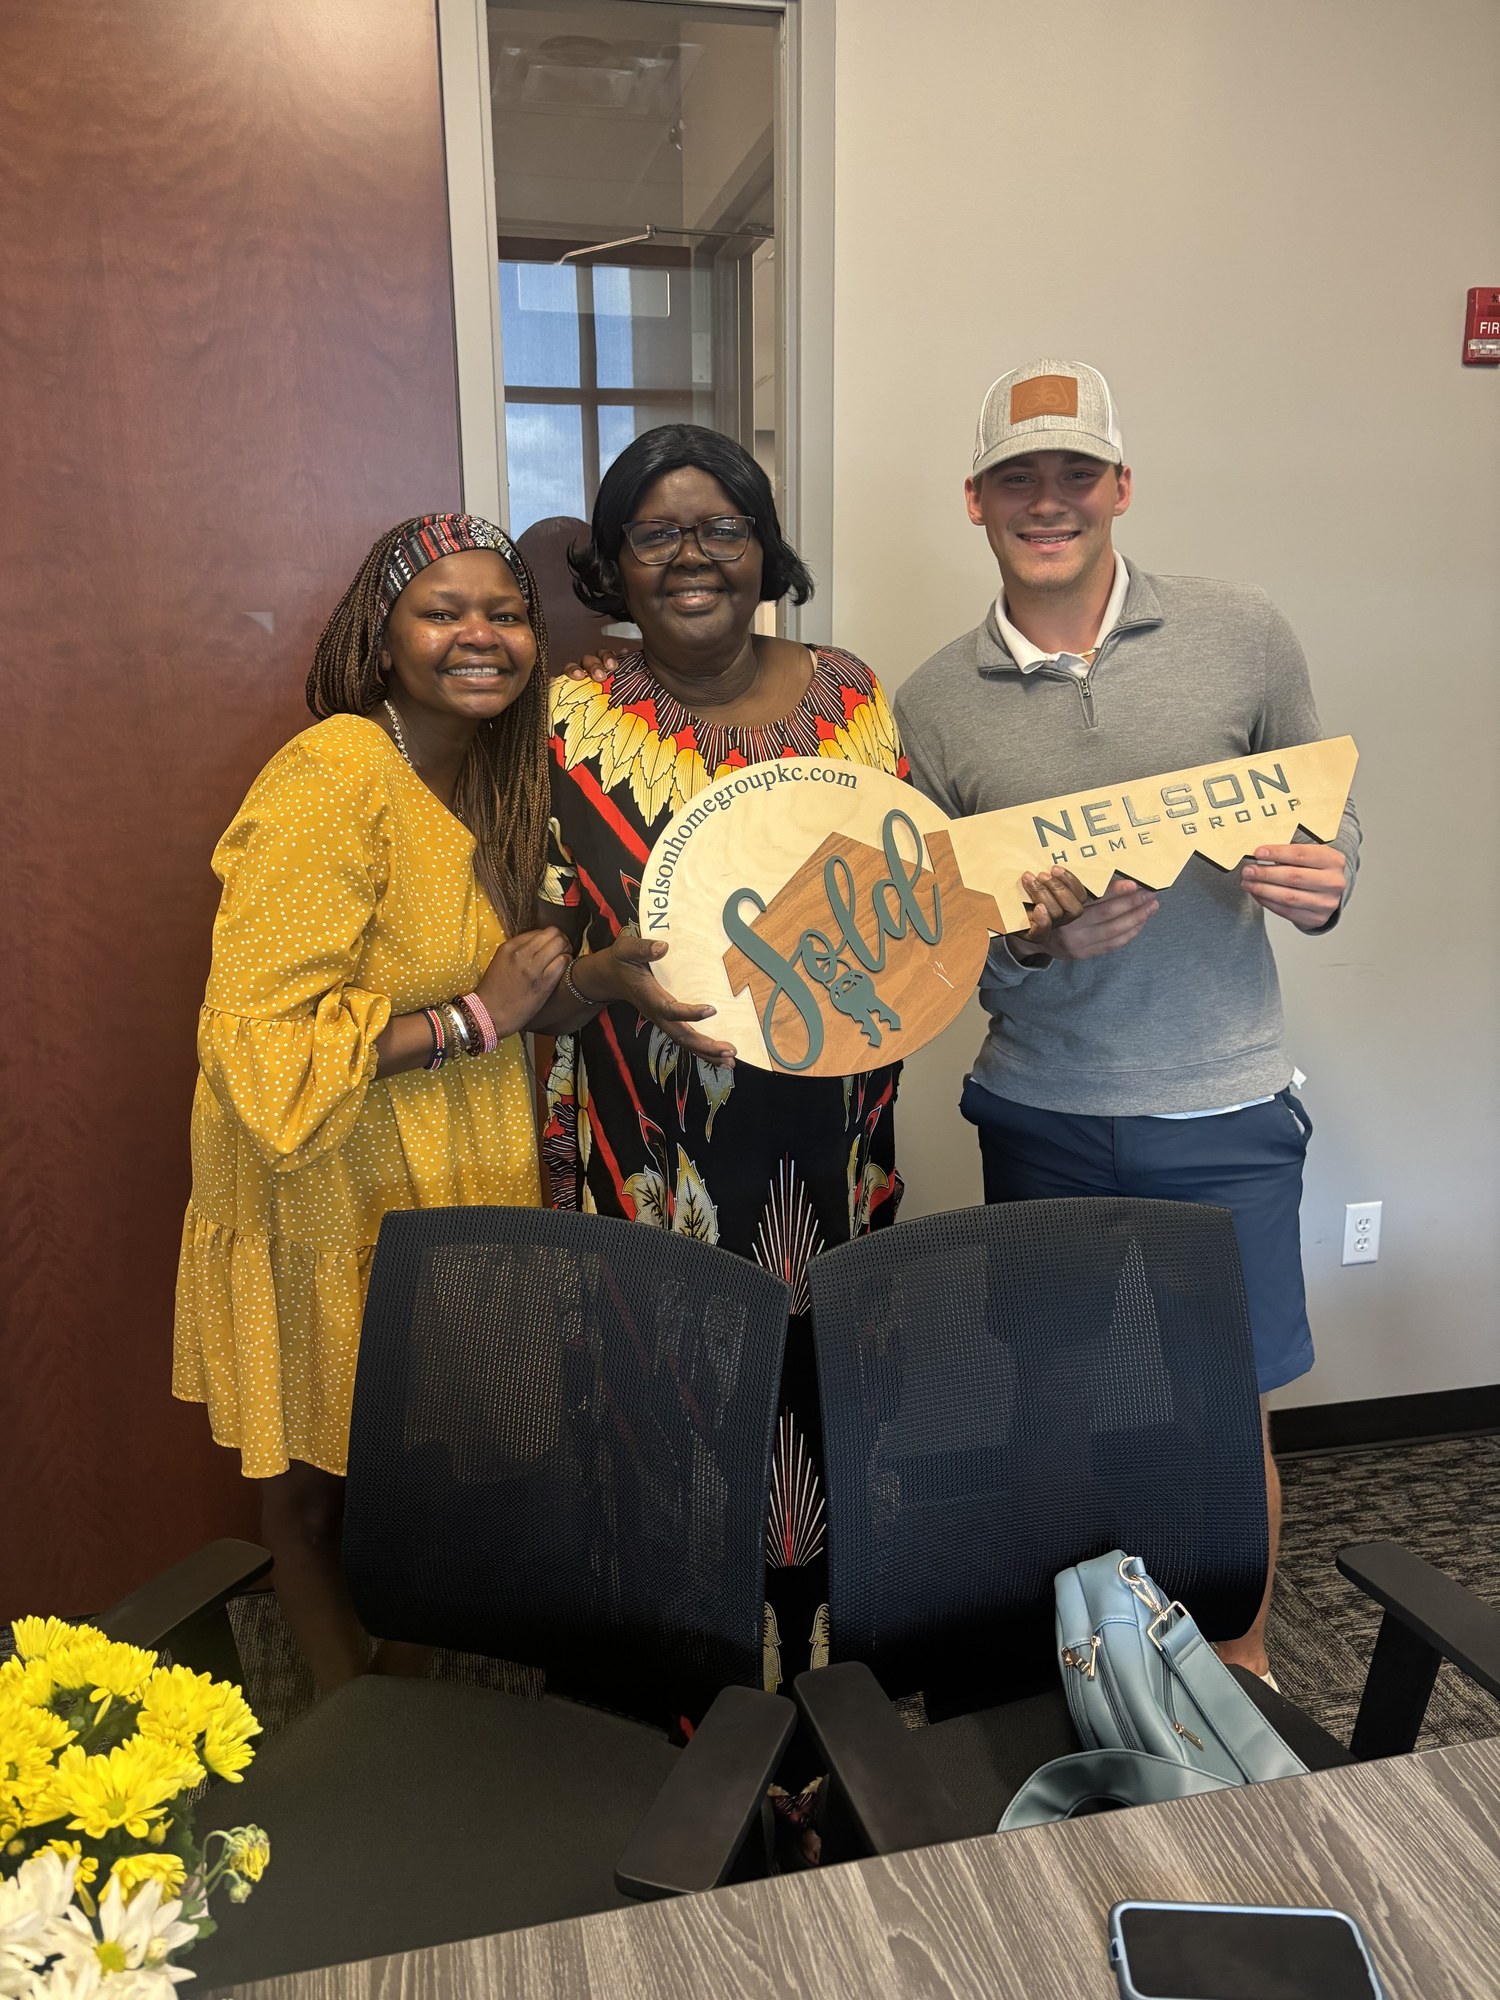
The part that does not show up on the MLS sheet: a family that trusted this team with a first home seven years ago trusted it again, and the newest agent on the team closed his first transaction with flowers on the closing table and a client who understood every page she signed. Asked whether she would recommend the approach to someone in her situation, the buyer said: “Yes. Especially for a first-time buyer, I’d definitely recommend having someone guide you through the process.”
“I was surprised by how smoothly everything went and how Danny helped make the numbers work.”
In Their Own Words
Elizabeth posted this publicly on Google after closing. Nobody asked her to.
“Seven years ago, Joe Nelson helped me buy my very first home. When it came time for my mom to purchase her house, we returned to the same team and had the absolute privilege of being Danny Stansbury’s very first sale! I stepped in to translate for my mom throughout the process, and Danny was incredibly patient, respectful, and attentive to every single detail. If he hadn’t told us, we never would have guessed he was new to the business. He handled everything with total professionalism, made sure my mom felt comfortable at every step, and even surprised us with beautiful flowers at closing. The same excellent standard of service we experienced years ago clearly continues with him. We are so proud to be his first clients and highly recommend him!”
About This Property
This home is a 1953 ranch in the Crestview subdivision of Kansas City, Missouri: two bedrooms, one full bath, 688 square feet on a single level over a crawl space, an attached one-car garage, a covered front porch and a fenced backyard with a patio on a 0.14-acre lot. Wood siding, composition roof, laminate floors, an eat-in kitchen with updated white cabinetry and a subway-tile backsplash, ceiling fans, and central electric heating and cooling on city water and sewer. Fiber internet is available. No HOA. Clay County; North Kansas City School District — Crestview Elementary, Eastgate Middle and North Kansas City High School.
The listing was held by Epique Realty; Nelson Home Group represented the buyer. More on the area: Living in Kansas City, MO →
Living in the Northland — Kansas City, Missouri
Crestview sits in the Northland, the part of Kansas City north of the Missouri River in Clay County, just east of Gladstone and a few minutes from the North Kansas City and Antioch commercial corridors along I-35 and Vivion Road. Ranch homes from the 1950s on modest lots make up most of the neighborhood, which is why it is one of the places in the metro where a first-time buyer can still find a detached house with a garage and a yard at a price FHA financing reaches. If you are weighing the Northland against the rest of the metro, our Kansas City agent page and the Kansas City, MO market page have more on how the market here actually behaves.
Frequently Asked Questions
How much money do I need to bring to closing as a first-time home buyer in Kansas City?
It depends on your loan program, your down payment, your closing costs and prepaids, and any credits or concessions negotiated into the contract — not on the purchase price alone. In June 2026 a first-time buyer represented by Nelson Home Group of Keller Williams KC North closed on a home in the Crestview subdivision of Kansas City, Missouri with FHA financing and $6,323 in seller-paid concessions, and brought less than $1,000 to the closing table. Our breakdown of what it actually costs to buy a house in Kansas City walks through each line item.
Can seller concessions cover my closing costs?
Often, yes. A seller concession is a credit the seller agrees to give the buyer at closing, and it can be applied to eligible closing costs and prepaids depending on the loan program and its limits. On this Kansas City purchase the offer was written above the list price and the seller credited $6,323 back, so the buyer financed those costs inside the loan instead of paying them in cash. The home has to appraise at the contract price for this to work, and your lender sets the cap on how much can be credited.
Do I need thousands of dollars saved to buy my first house?
Not necessarily. What you need depends on your financing and the terms you negotiate, and a first-time buyer with limited cash has more options than most people assume. Get an estimated cash-to-close from your lender in writing before you decide you cannot afford to start — that estimate, not the list price, is the number that tells you whether a purchase is possible.
What happens if I don’t have enough money to close on my first house?
Do not walk away before running the actual numbers with your lender and your agent. Depending on the situation there may be loan programs with lower down payments, negotiated seller concessions, lender credits, or down payment assistance that reduce the cash you need. The buyer in this story was worried about exactly this and closed with less than $1,000 at the table.
Can I use an FHA loan as a first-time buyer in Missouri?
Qualified buyers can, and FHA is one of the most common loan programs for first-time buyers in the Kansas City area because of its 3.5 percent minimum down payment and flexible credit requirements. This purchase closed on FHA financing in 33 days from contract. A lender can confirm the requirements and whether it fits your situation.
Will a seller accept an FHA offer that asks for concessions?
It depends on the seller’s situation and on how credible your financing looks. This seller had just lost a buyer whose financing fell apart on closing day, and still accepted an FHA offer with a $6,323 concession request — because the buyer’s file was solid, the lender was responsive, and the offer was written above list so the seller’s net held up. The sellers we represent weigh the same things; our post on how a buyer’s loan type looks from the seller’s side explains what they are looking at.
Can I buy a house in Kansas City if I don’t speak English well?
Yes. Many buyers go through the process with a family member translating, and that is how this Kansas City purchase was handled — the buyer’s daughter translated at every step, and every number and document was explained until both of them understood it. Ask your agent and your lender up front how they will make sure you fully understand every document before you sign.
Should I get pre-approved before I start looking?
Yes, and do it before you fall in love with a house. A full pre-approval tells you what you can actually afford and what your cash to close looks like, which is the number that surprises most first-time buyers. It also matters on the other side of the table: a seller who has watched a deal fall apart on closing day is going to look hard at your financing before accepting your offer. Nelson Home Group is not a lender or a tax advisor — your loan officer should give you these figures in writing.
Closing on a first home with less than $1,000 is not a trick and it is not luck. It is the right loan program, a concession negotiated into the contract, and an offer built so the seller says yes to both. If you are starting a search of your own, our first-time buyer guide is the place to begin.
More first-time buyer stories from our team: down payment assistance on a first home in Missouri · buying your first home before your lease runs out · what happens if your home purchase contract falls through · negotiating on a nearly new home in Lee’s Summit.
Nelson Home Group works with first-time buyers across the Northland and the wider Kansas City metro. Call 816-680-6624 or reach the team here.
Another first-time buyer story from our team: a 24-year-old first-time buyer in the Raytown area bought with an FHA loan, under list, with the sellers covering his closing costs.
Joe Nelson · Nelson Home Group · 1508 NW Vivion Rd #205, Kansas City, MO 64118 · 816-680-6624
Brokerage: Keller Williams KC North · 816-452-4200
Another first-time buyer story from our team: how an FHA offer won a Ruskin Hills ranch in south Kansas City on a listing marked cash or conventional, one of three offers, with seller concessions toward closing costs.
The Result
Under $1,000 at Closing on a First Home
FHA · $6,323 in seller concessions · closed June 16, 2026
Crestview · Kansas City, MO
A first-time buyer’s biggest worry was cash to close. The offer was written to solve it.

Buying Your First Home?
The number that decides whether a first purchase happens is cash to close, not the list price — and it can be negotiated. Start with How to Buy Your First Home in Kansas City, or talk to our team.
How the Timeline Actually Ran
- March 23, 2026 — listed
- A first contract fails when that buyer’s financing falls apart on closing day; the home comes back on the market
- May 14, 2026 — under contract with our buyer, FHA, $6,323 in concessions
- June 16, 2026 — closed, 33 days later
The MLS records 13 days on market for the relisted period.
What Makes Up “Cash to Close”
- Down payment — 3.5% minimum on FHA
- Lender fees and the appraisal
- Title and settlement charges
- Prepaid taxes, homeowners insurance and interest
- Minus your earnest money, lender credits and seller concessions
The last line is where the negotiation lives. Ask your lender for the estimate in writing before you shop.
How a Seller Concession Actually Works
- The offer is written above the list price
- The seller credits part of it back at closing
- The credit pays eligible closing costs and prepaids
- The buyer finances that money inside the loan instead of paying cash
- The home must appraise at the contract price
The seller nets about the same. The buyer keeps their savings. Your lender sets the cap on how much can be credited.
Why the Seller Said Yes
- The previous buyer’s financing had failed on closing day
- Our buyer’s file was fully underwritten and the lender was responsive
- The offer above list protected the seller’s net
- A clean timeline with nothing left to move later
A seller who has been burned buys certainty. That is what this offer sold.
The Numbers on This Crestview Home
- 2 bedrooms, 1 full bath
- 688 sq ft on one level · crawl space
- Built 1953 · ranch · attached 1-car garage
- 0.14-acre fenced lot with a patio
- No HOA
- FHA · $6,323 in seller concessions · under $1,000 cash to close
Clay County, Missouri. North Kansas City School District.
FHA Basics for a First Home
- 3.5% minimum down payment for qualified buyers
- Sellers may contribute up to 6% of the price toward closing costs
- Mortgage insurance is built into the payment
- The appraisal checks condition as well as value
Program rules change and every file is different — confirm the current limits with your lender.
Questions to Ask Your Lender Before You Shop
- What is my estimated cash to close, in writing?
- How much can the seller credit toward my costs on this loan?
- Is there down payment assistance I qualify for?
- How fast can you close if the seller needs certainty?
Nelson Home Group is not a lender. These are the questions we make sure our buyers get answered before the first showing.
About Danny Stansbury
Danny Stansbury is a Realtor with Nelson Home Group at Keller Williams KC North, born and raised in Kearney, Missouri. This Crestview purchase was his first closed transaction — run for a first-time buyer, through a translator, on a listing that had just lost a buyer to a financing failure. Read Danny’s full bio →
More First-Time Buyer Stories
- Down payment assistance on a first home in Missouri
- Buying your first home before your lease runs out
- When a home purchase contract falls through — Lee’s Summit
- Negotiating on a nearly new home — Lee’s Summit
Every one of these is a closed Nelson Home Group transaction, not a hypothetical.
What Does It Really Cost to Buy in Kansas City?
Down payment, closing costs, prepaids, reserves — our line-by-line breakdown of what it costs to buy a house in Kansas City puts numbers on each one, or ask us about your situation.